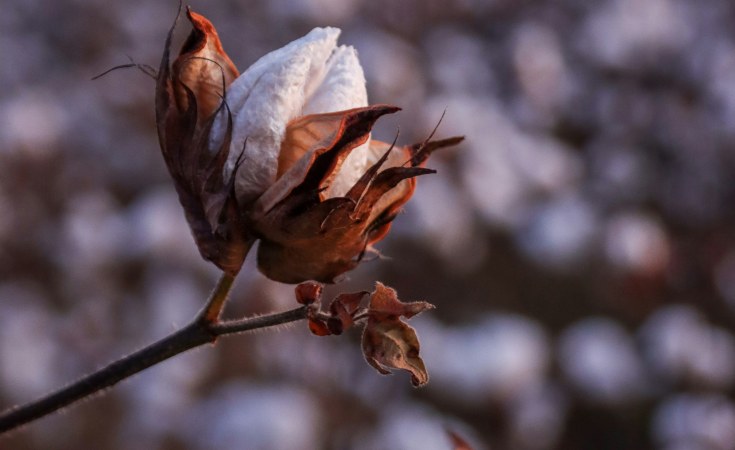
When a matter is too serious to settle in passing, a palaver is called. Elders and neighbours sit down, arguments are tested, and the conversation continues until the truth has nowhere left to hide. Africa's cotton belongs under that tree.
The continent has never lacked the ability to grow the crop. Across West and Central Africa, cotton supports farmers, traders, transporters and entire rural economies. Yet the World Trade Organization says that roughly 98 per cent of cotton from the C-4+ countries - Benin, Burkina Faso, Chad and Mali, together with Côte d'Ivoire - still leaves the region as raw fibre.
The question is disarmingly simple: why should Africa export the fibre and import the shirt?
Follow us on WhatsApp | LinkedIn for the latest headlines
A bale of cotton is only the beginning of an industrial story. Ginning separates fibre from seed. Spinning turns fibre into yarn. Weaving and knitting make fabric. Dyeing, finishing, cutting and sewing turn that fabric into products people buy. At every stage, value rises. Skills deepen. Businesses multiply. Jobs are created in production, design, logistics, maintenance, packaging, finance and retail.
When those stages take place elsewhere, Africa does not merely lose a higher export price. It gives away the industrial ecosystem that forms around production. Cotton is therefore not simply an agricultural commodity. It is a test of whether the continent can connect farming to manufacturing and manufacturing to markets.
That test is becoming more urgent. The African Development Bank estimates that 10 million to 12 million young Africans enter the labour market each year, while only about 3 million formal jobs are created. Garment manufacturing cannot close that gap on its own, but it is one of the industries capable of absorbing large numbers of workers while creating routes into more specialised production.
Ethiopia's Hawassa industrial zone demonstrated both the promise and the fragility of that model. Employment there rose to about 33,000 before falling to roughly 18,000 as buyers and orders declined after Ethiopia lost access to the United States market under the African Growth and Opportunity Act in 2022, according to the World Bank. Factories can create jobs at scale. They can also shed them quickly when an industrial strategy depends too heavily on a single trade preference or destination market.
Nigeria is now making a different wager. The Ogun State government and ARISE Integrated Industrial Platforms have announced plans for a garment hub presented as a $2 billion investment. State authorities say the proposed facility is intended to process cotton at scale, produce millions of garments and generate extensive direct and indirect employment. Those numbers are targets, not operating results. Their importance lies in the direction of the proposal: cotton farming, processing, manufacturing and logistics are being conceived as parts of one productive system.
A broader continental initiative points in the same direction. Afreximbank, ARISE IIP and the textile-machinery company Rieter have launched an Africa Textile Renaissance Plan. The partners say the programme aims to mobilise $5 billion in financing, establish 500,000 tonnes of additional cotton-processing capacity over three to five years and support up to 500,000 jobs. Again, these are ambitions to be delivered, not achievements already banked. But they recognise the scale at which the missing industrial links must be built.
The African Continental Free Trade Area could make those investments more viable. It brings together a market of more than 1.3 billion people with combined output of about $3.4 trillion. World Bank modelling suggests that deeper implementation could raise continental income by 9 per cent and create 18 million jobs by 2035. Those gains are conditional, not automatic. A tariff-free border does not turn raw cotton into fabric. It rewards countries and companies that have already developed products, standards, logistics and dependable production.
This is why market access alone cannot carry Africa's textile industry. Trade preferences can disappear. International cotton support programmes can depress prices and alter competition. Cheap imported fabric can overwhelm domestic factories. Electricity failures, expensive credit and weak transport can make an otherwise viable mill uncompetitive before its first order is shipped.
The financing gap is real, but finance is not the only missing element. A spinning mill needs a predictable supply of cotton of consistent quality. A garment factory needs fabric, power, water, skilled supervisors, working capital and reliable buyers. Producers need standards that open markets rather than become barriers at the border. Governments need procurement and trade policies that encourage local production without sheltering permanent inefficiency.
Scale also requires regional thinking. Smaller cotton producers such as Senegal, Togo, Ghana and Niger may struggle to justify every stage of the value chain within their own borders. Shared infrastructure, regional spinning capacity and coordinated logistics could change the economics. AfCFTA will matter most when it allows neighbouring countries to specialise within a connected production system rather than duplicate incomplete industries behind national frontiers.
There is another issue to place before the palaver tree: protection after construction. Africa's industrial debate often ends when a factory opens. The harder work begins afterwards. Can the business obtain inputs at a competitive price? Can it survive currency volatility? Can it reach regional customers? Can it upgrade machinery and skills? Can local design and intellectual property withstand imported imitation? An industrial policy measured only in ribbon-cuttings is not an industrial policy.
Sign up for free AllAfrica Newsletters
Get the latest in African news delivered straight to your inbox
Nor should the continent's young population be discussed only as a crisis. Millions of people entering the labour market are also a vast productive capacity. But labour becomes an advantage only when workers can acquire skills, firms can invest and factories can sell what they produce. The demographic dividend is not waiting to be discovered. It has to be organised.
Africa's cotton reckoning is therefore not about potential. Potential has become the continent's most overused alibi. The fields already exist. The workers already exist. The market is being assembled. What remains is the deliberate construction of the stages between fibre and finished product - and the discipline to keep them competitive once they are built.
The question was never whether Africa could grow cotton. It already grows cotton for the world. The question is how much of what that cotton becomes Africa is prepared to keep.
#AfricaMadeIt #MakeItInAfrica #BuildingforPower
